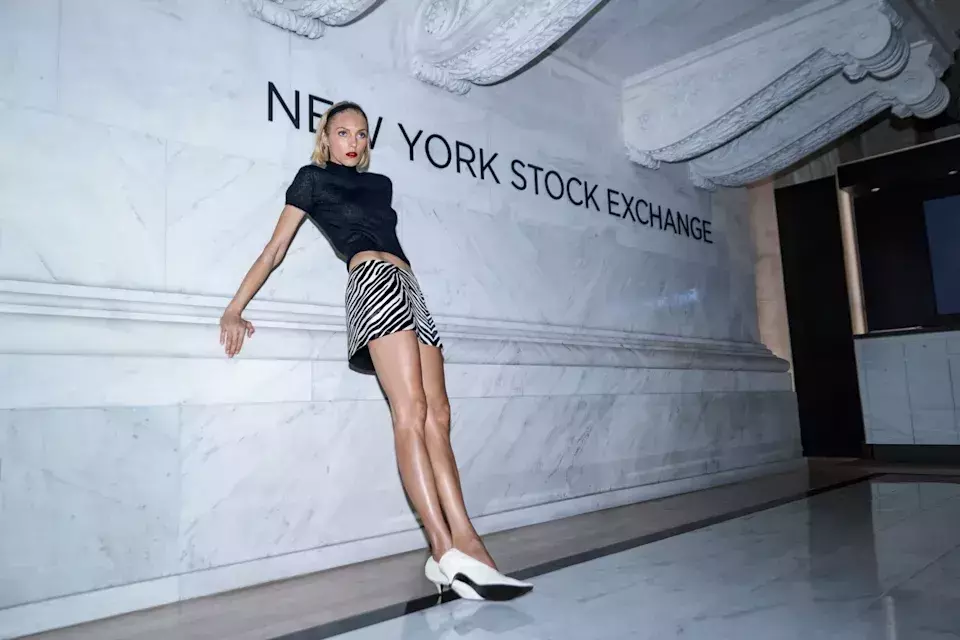
Reformation IPO: A Sustainable Investment for Your Portfolio
Reformation Inc., a prominent name in sustainable fashion, recently made its initial public offering, pricing shares at $15. This move introduces a company to the stock market that has demonstrated remarkable financial health and a resilient business model. Since 2015, the company has seen an impressive annualized revenue growth of 34%, with a 30% increase in the first quarter of 2026 alone. A significant driver of this success is its loyal customer base, with 70% of 2025 direct-to-consumer revenue stemming from repeat buyers. This enduring appeal spans various age groups, primarily attracting customers between 25 and 50 years old, many of whom boast annual household incomes exceeding $100,000. Originally known for its dresses, Reformation has strategically broadened its product offerings to include denim, footwear, and accessories, targeting a vast untapped market within the women's 18-60 demographic in the U.S. The company's valuation at 1.5 times its projected 2027 sales appears conservative when compared to industry peers like Aritzia Inc. and Ralph Lauren Corp., indicating a potentially attractive entry point for investors.
The journey of Reformation began in Los Angeles in 2009, with a focus on revamping vintage apparel through sustainable practices. Over the years, it has transformed into a global enterprise, achieving over $500 million in sales last year. This growth is underpinned by 21 consecutive quarters of double-digit revenue expansion, a testament to its consistent market performance. The brand's ability to forge deep connections with its clientele is a cornerstone of its business. For instance, its product lines resonate across generations, appealing to millennials, Gen X, and Gen Z alike. This cross-generational appeal is often observed in its stores, where mothers and daughters frequently shop together, finding items that suit their individual styles.
Beyond its diverse product range and broad customer appeal, Reformation excels in customer engagement and operational efficiency. The company's direct-to-consumer model accounts for 90% of its revenue, with e-commerce making up two-thirds of that figure. Notably, customers are willing to pay full price for items, with approximately 80% of direct-to-consumer sales coming from full-priced merchandise in recent years. High-spending customers, those who spend over $1,000 annually and make multiple purchases, are invited to the exclusive 'Friends with Benefits' program. This loyalty initiative offers perks such as early access to new collections and sales, along with direct communication channels to Reformation experts, reinforcing customer retention among its affluent base.
Technological integration also plays a crucial role in Reformation's operational prowess. The company leverages purchase data to make real-time inventory decisions, facilitating the frequent introduction of new products—twice weekly online and weekly in stores. Its supply chain is exceptionally efficient, with 50% of products reaching distribution centers within 60 days of order. Furthermore, Reformation strategically aligns its releases with current cultural and fashion trends, garnering organic media attention and customer interest. This approach, combined with word-of-mouth and social media engagement, allows the brand to acquire 75% of its new direct-to-consumer customers through unpaid channels, minimizing marketing expenditures.
Reformation's retail locations function as modern showrooms, offering an immersive shopping experience. These stores maintain ample inventory for immediate purchases and incorporate technology that allows customers to explore different styles and sizes directly from fitting rooms. These physical spaces also complement the brand's online presence, enabling customers to discover items in person and later purchase them via their smartphones. With nearly a fifth of its 2025 revenue derived from international buyers, Reformation boasts a robust global footprint, with operations in Canada, the U.K., and France, and substantial potential for further expansion into new markets.
The cumulative effect of these strategic elements translates into compelling financial indicators. In addition to its impressive revenue growth, Reformation has maintained positive EBITDA for several years, with projections for margin expansion. Last year, the company achieved an EBITDA margin of 8.9%, which is anticipated to grow to 16% by 2028, according to Renaissance Capital. The conservative pricing of its IPO at $15 per share, representing an enterprise value of just 1.5 times its expected 2027 sales, positions Reformation favorably in the market. This valuation is considerably lower than those of its peers, Aritzia Inc. at 3.3 times and Ralph Lauren Corp. at 2.7 times, presenting an attractive proposition for new investors. The company's unique blend of growth, profitability, and an exceptionally loyal customer base makes its IPO a compelling opportunity to enhance a diversified investment portfolio.
