Bank of America Upgrades Tesla's Financial Outlook Ahead of Q2 Earnings
Bank of America has significantly updated its financial projections for Tesla, raising revenue and earnings per share estimates for the years 2026 through 2028. This optimistic revision, which includes a reaffirmed 'Buy' rating and a price target of $460, comes as Tesla approaches its second-quarter earnings report on July 22, 2026. The bank's confidence stems from Tesla's unexpectedly strong vehicle deliveries, the expansion of its robotaxi services, and the anticipated growth from its Optimus humanoid robots and energy storage solutions. Despite recent challenges, including a decline in SpaceX's stock, market attention is firmly focused on Tesla's ability to translate these emerging opportunities into tangible financial gains, particularly given that current valuation models rely on speculative long-term assumptions.
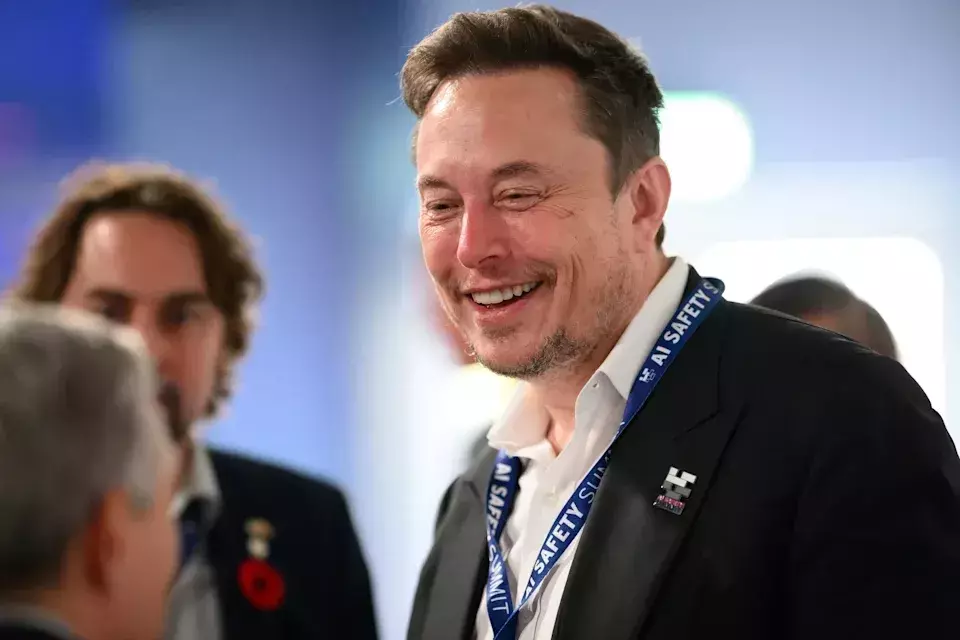
Elon Musk, the visionary leader behind Tesla, has recently navigated a period of mixed fortunes. His other venture, SpaceX, saw its Starship launch aborted, causing its stock to fall below its initial public offering price. However, the investment community's focus quickly shifted to Tesla, anticipating its upcoming Q2 earnings. The electric vehicle giant has demonstrated improved delivery figures, a notable expansion of its robotaxi initiatives, and increasing expectations for its Optimus project and energy storage developments. Bank of America analysts point to these factors as key drivers for their revised outlook, suggesting that the most significant changes for Tesla might be occurring beyond the traditional earnings metrics.
The core of Bank of America's bullish stance on Tesla is largely anchored in the potential of its burgeoning technologies, with robotaxis identified as a primary catalyst. Tesla has already launched robotaxi operations in five major markets, including a recent debut in Miami, with plans for four more cities underway. While the company missed its initial target of nine cities by mid-2026, the growth in active fleets, such as the impressive surge in Texas, indicates strong momentum. However, challenges remain, including the continued use of safety drivers in some markets and a disparity in arrival times compared to competitors, suggesting demand may outstrip current supply or that fleet density and dispatch efficiency still need optimization. Despite these operational hurdles, initial safety data for Tesla's robotaxis appears promising, with 22 reported incidents through mid-June, none involving serious injuries or fatalities, albeit with significantly less cumulative mileage than rivals like Waymo.
Beyond the innovative frontier of robotaxis, Tesla's traditional automotive sector has also shown encouraging signs. The company exceeded expectations with approximately 480,000 deliveries in Q2, a 25% increase year-over-year and significantly higher than consensus estimates. This performance suggests Tesla is expanding its global battery-electric vehicle market share, particularly as established automakers scale back their less profitable EV production. Importantly, this growth in deliveries did not necessitate further aggressive price cuts, though pricing remains below its 2022 peak. Additionally, the Optimus humanoid robot project, which Musk has proclaimed could be Tesla's most significant product, is progressing with initial production slated for late July or August at Fremont, and Texas production expected in 2027. The company's 25-GWh NatPower Megapack deal further solidifies energy storage as a robust and established growth area.
While Bank of America's $460 price target signals strong confidence, it's crucial to note that this valuation is not solely based on Tesla's automotive revenue. The bank employs a complex valuation methodology that combines an 8-times enterprise value to EBITDA for the automotive business with separate discounted cash flow (DCF) models extending to 2040 for Robotaxi, FSD, Optimus, and Energy. These long-term DCF analyses rely on ambitious assumptions, such as a 40% penetration rate for Optimus in U.S. manufacturing and 35% in U.S. households, and a 4.5% terminal growth rate for Robotaxi. Such extended projections, sensitive to minor changes in discount rates and growth assumptions, make the target harder to independently verify. Furthermore, the operating forecast indicates that while margins are expected to recover, free cash flow is projected to turn negative between 2026 and 2028, highlighting potential financial pressures despite the overall positive outlook.
