Unlock Double Your Retirement Income with This 401(k) Strategy Before Age 59.5
Secure Your Financial Freedom: Maximizing Early Retirement Payouts
A Strategic Approach to Enhanced Early Retirement Income
For individuals with substantial 401(k) savings, a key challenge is accessing these funds before age 59.5 without facing a 10% early withdrawal penalty. While many standard options offer limited flexibility, a specific strategy utilizing IRC Section 72(t) for Substantially Equal Periodic Payments (SEPP) provides a robust solution. This method, particularly the fixed amortization approach, can nearly double the annual income from a $1 million IRA compared to the default Required Minimum Distribution (RMD) method, transforming a modest four-year bridge into a genuine early retirement income stream.
Exploring the Varied SEPP Calculation Methods
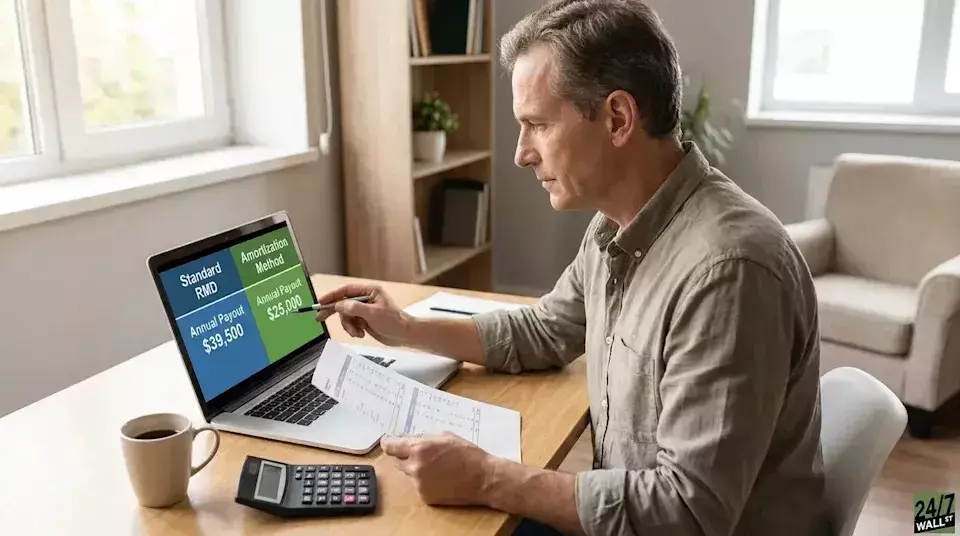
The IRS recognizes three primary methods for calculating penalty-free SEPP withdrawals: the Required Minimum Distribution (RMD) method, the fixed amortization method, and the fixed annuitization method. While all three are permissible, the RMD method often results in a significantly lower annual payout, making it less attractive for those seeking a substantial early retirement income. For example, a 55-year-old with a $1 million traditional IRA, using the RMD method, would withdraw approximately $31,600 annually, which many consider insufficient for a comfortable retirement. This disparity underscores the importance of understanding and selecting the most beneficial calculation method.
Unlocking Higher Payouts: The Power of Amortization
The fixed amortization method offers a far more generous payout. This approach treats the IRA balance much like a reverse mortgage, distributing funds over a calculated period using an IRS-approved interest rate. Currently, with a 5% floor rate often applicable, amortizing $1 million over 31.6 years yields an annual payment of roughly $63,600. This figure is more than double the RMD method's output. The annuitization method typically provides a similar result, reinforcing that choosing either of these two methods over the RMD approach can dramatically enhance your early retirement income from the same account, with the same balance, and under the same IRS regulations.
Navigating the Commitment of SEPP Distributions
A crucial aspect of the SEPP strategy is the binding commitment it requires. Once initiated, these payments must continue without alteration for the longer of five years or until the account holder reaches age 59.5. Any deviation from this schedule, such as taking an additional withdrawal, ceasing payments early, or rolling over the account, will trigger a retroactive 10% penalty on all distributions made since the beginning, plus interest. This strict adherence requirement makes ages 55 to 57 an optimal window for initiating SEPP, as the five-year commitment period often aligns closely with reaching the 59.5 age threshold, providing maximum flexibility. For those who retire earlier, such as at age 50, the extended commitment period can pose a greater risk to financial stability.
Understanding the Tax Implications of Early Withdrawals
While the SEPP strategy can significantly boost early retirement income, it's essential to consider the tax implications. A $63,600 SEPP distribution is classified as ordinary income. For a single filer in 2026 without other wages, this income, after subtracting the standard deduction, could place them in the 22% tax bracket. If additional income sources, such as a spouse's wages or a pension, are present, the top portion of the income could be taxed at 24%. Furthermore, once Social Security benefits commence, SEPP distributions can lead to up to 85% of those benefits becoming taxable and may even trigger the first IRMAA (Income-Related Monthly Adjustment Amount) threshold two years later. Given that few retirees achieve the "seven-figure early retiree" status, this strategy particularly benefits those with substantial savings.
Strategic Steps for Optimizing Your Retirement Plan
To effectively implement this strategy, several proactive steps are recommended. First, compare the payouts from both the RMD and amortization SEPP calculators, using the IRS single life table and the current 5% floor rate. If the amortization figure doesn't comfortably cover your annual expenses, consider alternative paths like the Rule of 55 or a taxable-bridge account. Second, consider splitting your IRA before starting SEPP. For example, dividing a $1 million IRA into a $700,000 SEPP account and a separate $300,000 emergency IRA provides crucial flexibility without disrupting the fixed payment schedule. Finally, meticulously model your tax situation through age 73. A doubled early retirement income taxed at 22% can be a significant advantage compared to the potential collision of RMDs, Social Security, and IRMAA in your mid-70s. For those whose combined income later approaches the first IRMAA tier, consulting a fee-only financial planner for Roth conversion strategies can prove invaluable.
