Revenue Performance of Chubb and Travelers: A Comparative Insight for Investors
Money

Revenue Performance of Chubb and Travelers: A Comparative Insight for Investors

authorBy T. Harv Eker
DateJul 04, 2026
Read Time3 min
This article offers a comparative analysis of the revenue trajectories of two prominent insurance corporations, Chubb and Travelers Companies, providing valuable insights for potential investors. It examines their distinct operational models, revenue generation strategies, and recent financial performances to shed light on their market positions.

Unpacking the Financial Narratives of Insurance Leaders

Chubb's Revenue Dynamics: Navigating Global Markets

Chubb, a major player in the insurance sector, generates its income through a diverse portfolio of commercial property and casualty, agricultural, and life insurance offerings for a worldwide clientele. The company recently strengthened its market presence by partnering with Safe Harbor Marinas and strategically reduced its involvement in the shared property segment. For the quarter ending March 31, 2026, Chubb reported a net income margin of 16%.

Travelers Companies: A Consistent Approach to Income Generation

Travelers Companies primarily accrues revenue by delivering a comprehensive suite of commercial and personal property and casualty insurance products. These services are distributed through an extensive network of independent agents and brokers. The firm recently introduced an artificial intelligence tool to enhance claims analysis and joined a California-based sustainable insurance program. In the first quarter of 2026, Travelers recorded a net income margin of 14%.

The Crucial Role of Revenue for Individual Investors

For financial entities like Chubb and Travelers, revenue encompasses both interest and non-interest income, excluding interest expenses. It serves as a fundamental metric, indicating the total capital a business generates before accounting for operational expenditures. Understanding this figure is key for investors assessing a company's financial health.

Comparing Quarterly Income for Insurance Leaders

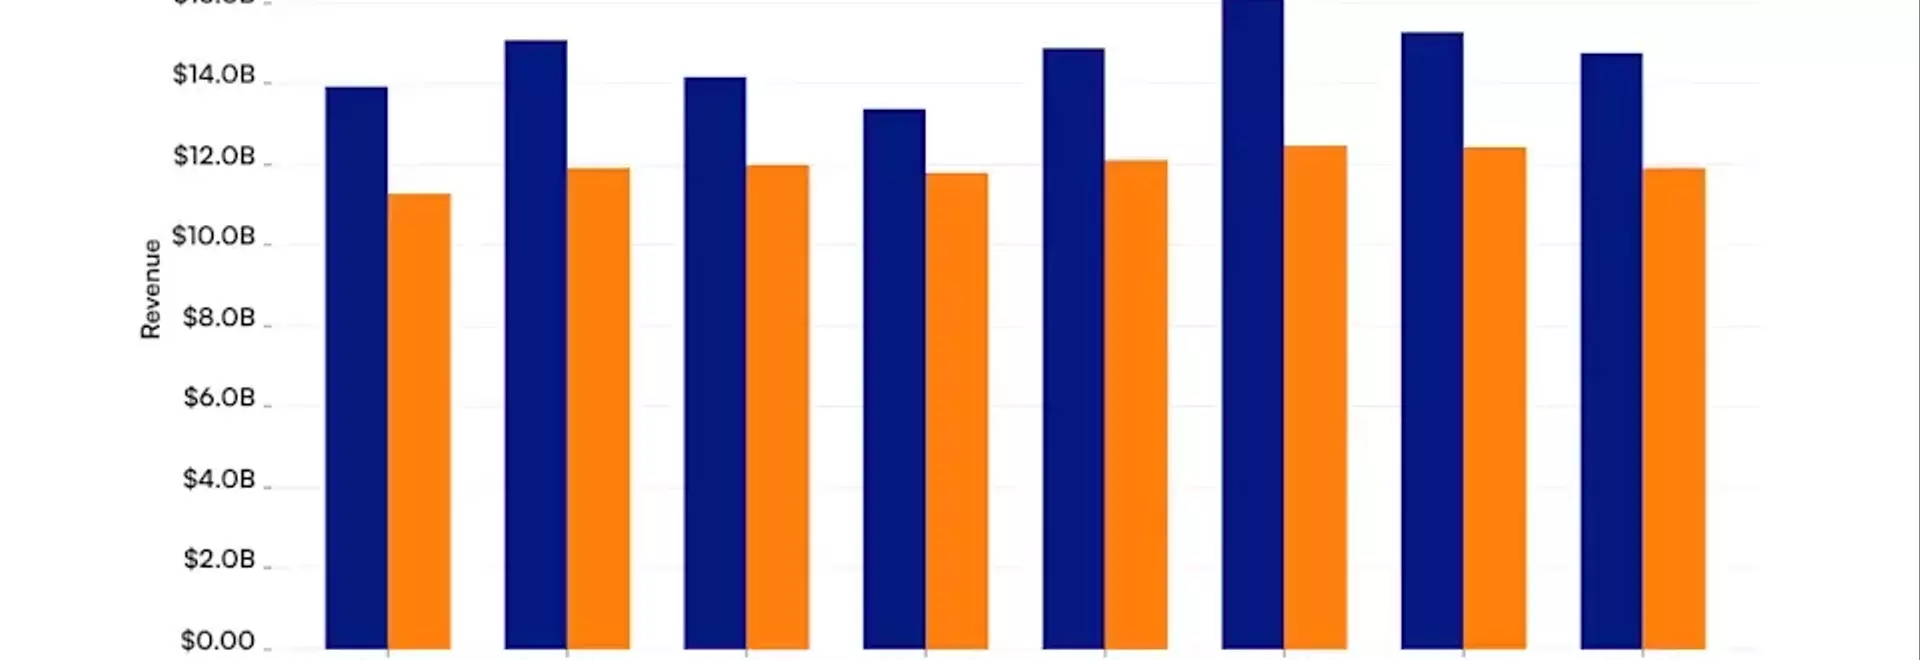
An examination of the quarterly revenue figures for Chubb and Travelers reveals contrasting patterns. Chubb's revenue exhibits greater variability quarter-to-quarter, largely attributable to its extensive global operations, with nearly half of its sales originating from international markets, making it susceptible to foreign currency exchange rate fluctuations. Conversely, Travelers demonstrates more consistent quarterly sales, primarily due to its strong domestic focus, with 93% of its 2025 revenue from the U.S. and further reduced international exposure following the sale of its Canadian operations in early 2026. Consequently, Chubb's overall sales volume is considerably higher than Travelers'. While quarterly revenue shifts are normal, a key indicator for investors is year-over-year sales growth. In this regard, Chubb has shown more robust expansion, with its first-quarter revenue reaching $14.8 billion, a 10% increase from 2025, whereas Travelers' sales grew by 1% in the same period. This difference underscores the growth potential that Chubb's global footprint offers compared to Travelers' U.S.-centric approach.

Beyond Revenue: A Look at Net Income Performance

While revenue is a critical metric, net income growth also plays a significant role in evaluating these companies. Both Chubb and Travelers delivered strong net income performances in the first quarter. Chubb's net income soared to $2.32 billion, marking a substantial 74% year-over-year increase. Travelers reported an even more impressive Q1 net income of $1.7 billion, representing a remarkable 333% surge, which contributed to its shares reaching a multi-year high of $342.31.

More Articles
Money
Microsoft's Strategic Positioning in AI and Technology: Xbox Pricing Amid Memory Market Shifts
Microsoft Corporation (MSFT) is solidifying its position as a top AI and technology stock, evidenced by recent Xbox price adjustments reflecting rising memory costs driven by AI demand. The broader consumer electronics sector is impacted by increased memory prices, as manufacturers prioritize high-bandwidth memory for AI infrastructure, like Nvidia's GPUs. Microsoft, a global tech leader, offers diverse software, cloud services, and hardware. While MSFT presents investment opportunities, some AI stocks may offer higher upside and lower risk, particularly those benefiting from current economic trends.
By T. Harv EkerJul 04, 2026
Money
Jim Cramer Predicts Continued Growth for Meta's Stock
Jim Cramer expresses bullish sentiment towards Meta Platforms (NASDAQ:META), believing the social media giant's stock has significant upside potential. He highlights Meta's strategic move to monetize its excess computing power through a cloud infrastructure business, similar to Amazon Web Services or Microsoft's Azure. Cramer suggests this shift will diversify Meta's revenue streams beyond advertising, leading to a more stable and enterprise-focused business model, ultimately boosting its valuation.
By Vicki RobinJul 04, 2026
Money
AMD Stock: A Prudent Investment Amidst Market Fluctuations
Financial analyst Jim Cramer views the recent downturn in Advanced Micro Devices (AMD) stock as a strategic buying opportunity. He underscores the company's strong position in both GPU and CPU markets, which are experiencing high demand. This article delves into Cramer's rationale and explores AMD's market standing.
By Bola SokunbiJul 04, 2026
Money
Piper Sandler Reiterates Overweight Rating on Meta Platforms (META) Stock
Piper Sandler analyst Thomas Champion reaffirmed an "Overweight" rating on Meta Platforms (META) stock, setting a price target of $800. Champion believes Meta's AI-powered agents and business messaging, particularly through WhatsApp in emerging markets, offer significant and often underestimated growth potential. The recent introduction of Meta's Business Agent product further supports this positive outlook, positioning Meta as a key player in the expanding enterprise AI market.
By Ramit SethiJul 04, 2026
Money
Medline Earns 'Best IPO' Acclaim from Jim Cramer
Financial commentator Jim Cramer has lauded Medline Inc. (NASDAQ: MDLN) as potentially the "best IPO of the year," based on its strong performance in the medical and surgical product supply sector. Despite this high praise, the article suggests that other AI-focused stocks might offer even greater short-term upside and reduced risk, particularly those benefiting from current economic trends. Investors are encouraged to explore alternative opportunities that align with these emerging market dynamics.
By JL CollinsJul 04, 2026