NXP Semiconductors Sees Price Target Hikes Amid AI-Driven Growth
NXP Semiconductors has recently been at the forefront of market discussions, with major financial firms like Citi, Wells Fargo, and Cantor Fitzgerald revising their price targets upwards. These adjustments reflect a growing confidence in the company's future, largely attributed to its strategic positioning within the analog semiconductor sector and the burgeoning influence of artificial intelligence across various industries. The sustained demand from AI data center expansions and the innovative potential of physical AI, such as humanoid technology, are key drivers behind this optimistic outlook.
Financial Analysts Boost NXP Semiconductors' Outlook with Increased Price Targets
In a series of recent announcements, leading financial institutions have significantly upgraded their price targets for NXP Semiconductors N.V. (NASDAQ:NXPI). On June 23, 2026, Citi substantially increased its target from $270 to $370, while maintaining a 'Buy' rating. This revision was underpinned by Citi's assessment of strong analog price upturns in June and the anticipation that AI data center developments would further prolong this positive trend.
Preceding this, on June 9, Wells Fargo also adjusted its price target for NXP Semiconductors, raising it from $265 to $305. The firm upheld an 'Equal Weight' rating, highlighting that the advancements in physical AI, particularly humanoids, present a significant long-term content opportunity for companies specializing in analog and mixed-signal technologies. Wells Fargo projected a semiconductor market opportunity of $1.6 billion by 2030 attributable to these innovations.
Adding to the chorus of positive revisions, last month, Matthew Prisco, an analyst at Cantor Fitzgerald, elevated his firm's price target for NXP Semiconductors from $340 to $380, reiterating an 'Overweight' rating. Prisco observed that the analog semiconductor cycle experienced a positive shift in the first quarter, marked by widespread beats and raises. This performance was primarily fueled by robust demand in the industrial and data center end markets. He also noted a fifth consecutive quarter of above-seasonal growth and improvements in cyclical indicators, including pricing, lead times, and order strength, despite ongoing challenges from more AI-focused segments.
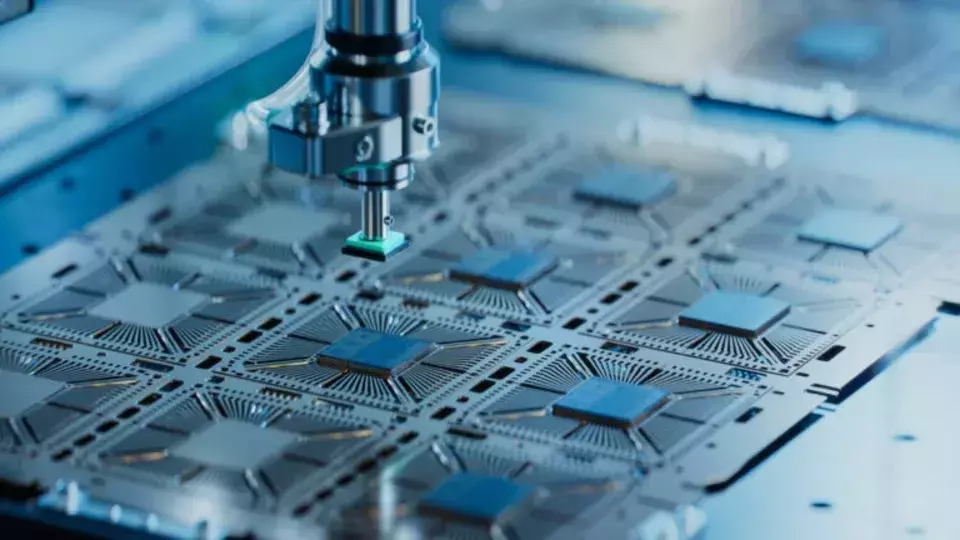
NXP Semiconductors N.V. is a global provider of semiconductor products, with extensive operations spanning the United States, Germany, Japan, South Korea, Taiwan, Singapore, the Netherlands, Mainland China, and Hong Kong. The company's diverse geographical presence underscores its significant role in the international semiconductor landscape. The image shows a close-up of silicon dies being extracted from a semiconductor wafer and attached to a substrate by a pick and place machine, illustrating the intricate process of computer chip manufacturing at a fab, specifically the semiconductor packaging stage.
While NXP Semiconductors presents a compelling investment case, some analyses suggest that certain other AI-focused stocks may offer even greater upside potential with reduced downside risk. For investors seeking highly undervalued AI stocks poised to benefit from current market trends, including trade policies and domestic production initiatives, further research into specific recommendations is advised.
The Future of Semiconductors: A Convergence of AI, Innovation, and Market Dynamics
The recent re-evaluation of NXP Semiconductors' market standing by prominent financial analysts underscores a critical trend in the technology sector: the escalating importance of artificial intelligence. This wave of upgraded price targets isn't merely a reflection of NXP's individual performance but signals a broader recognition of the semiconductor industry's pivotal role in enabling AI's explosive growth. As AI continues to permeate various applications, from vast data centers to sophisticated humanoid robotics, the demand for advanced analog and mixed-signal semiconductors will only intensify. This highlights not only the company's robust operational capabilities and strategic market positioning but also the profound impact of technological evolution on investment strategies. For investors, understanding these dynamics means looking beyond immediate gains to grasp the long-term potential fueled by such transformative technologies. The narrative suggests that while established players like NXP are adapting and thriving, the broader landscape of AI-levered stocks remains ripe with opportunities, urging a nuanced approach to portfolio diversification and growth seeking.
