easyJet Rejects Acquisition Offer, Citing Undervaluation
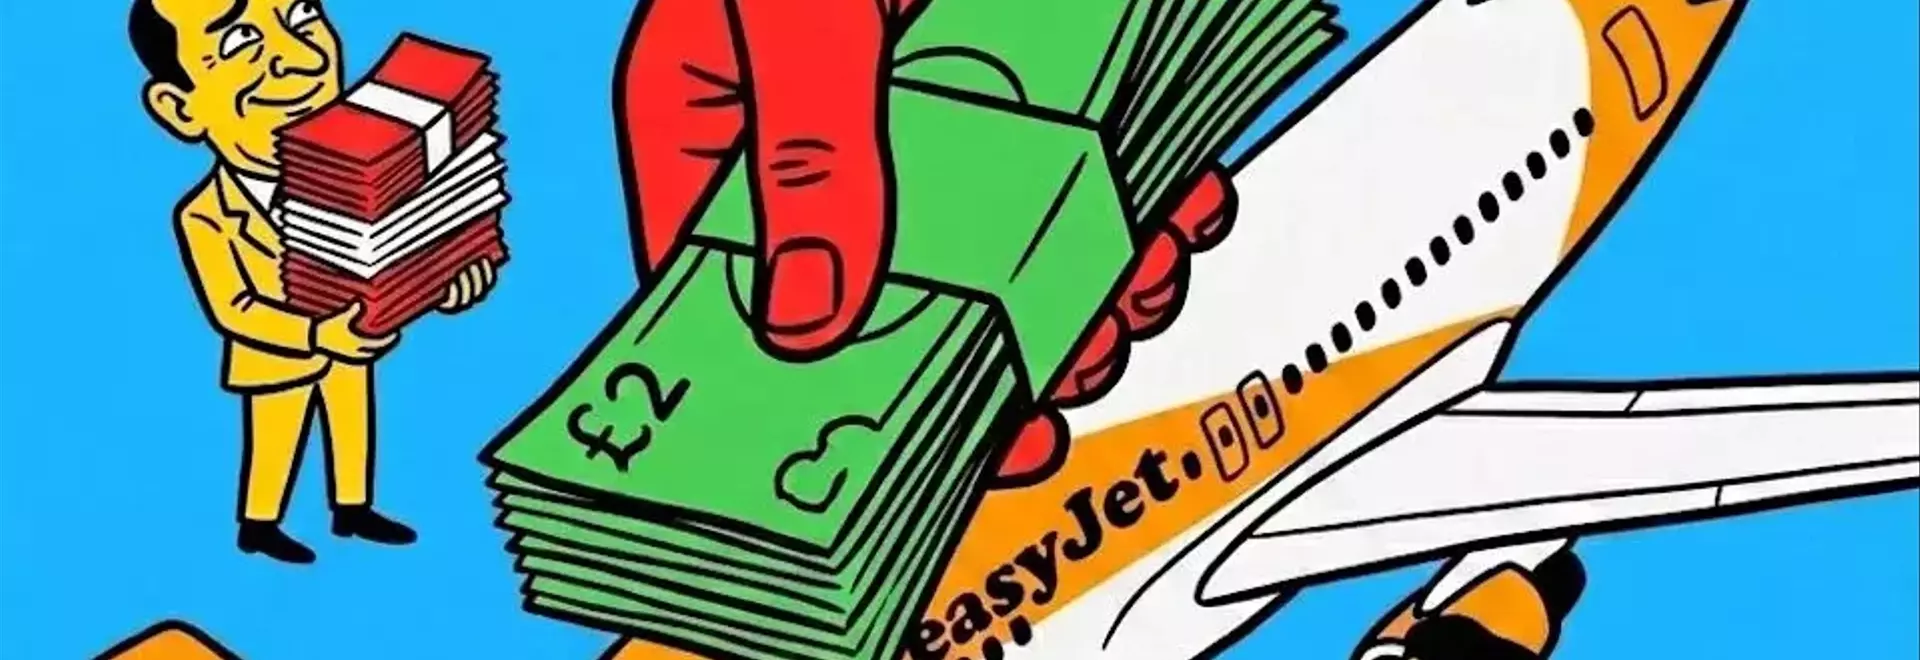
easyJet, the renowned budget airline, recently rebuffed a substantial £4.74 billion acquisition proposal from the private equity entity Castlelake. The airline's board cited a significant undervaluation of its assets and future growth potential as the primary reason for their unanimous decision. This move transforms what began as a quiet negotiation into a public debate regarding the appropriate valuation of one of Europe's largest low-cost carriers, particularly as it stands on the cusp of realizing the benefits of its strategic initiatives.
The unsolicited cash offer, originating from Minneapolis-based Castlelake, amounted to 625 pence per share. easyJet's management firmly believes this figure fails to capture the true worth of the company and its long-term outlook. This was not Castlelake's initial attempt; the firm had previously submitted bids of 560 pence and 600 pence per share within a week, only to be met with successive rejections.
Following the news, easyJet's London-listed shares saw a more than 4% increase, reaching approximately 525 pence. Investors are now closely monitoring whether Castlelake will escalate its offer or directly appeal to shareholders. Notably, Castlelake already holds a 2.14% stake in easyJet through its managed funds, providing it with a preliminary position. However, easyJet's board has consistently denied the private equity firm access to its financial records for due diligence, clearly indicating their unwillingness to entertain the current offer.
A crucial aspect of this potential takeover involves regulatory considerations. European airlines are mandated to maintain majority ownership and control by European nationals. To address this, Castlelake proposed establishing an EU-based holding company, with 51% ownership by European citizens. Peter Bellew, a former executive at Ryanair and easyJet, along with aviation consultant Mark Breen, were named as the majority partners, while Castlelake would provide the primary financial backing, holding a 49% stake. Reports also suggest that Goldman Sachs is prepared to facilitate the necessary debt financing for the proposed privatization.
The underlying dynamic at play here is characteristic of private equity operations: identifying an asset that appears temporarily undervalued in the public market, attributing this to market sentiment, and attempting to acquire it before its intrinsic value becomes widely recognized. easyJet's board, however, remains unconvinced by this narrative.
The airline's leadership contends that Castlelake is attempting to capitalize on a period when airline stocks are facing headwinds from fuel price fluctuations, geopolitical instability, wavering consumer confidence, and a general softening in travel demand. While these factors might present an attractive screen valuation, easyJet argues that this perspective overlooks its substantial progress and imminent turnaround. The company has dedicated years to restructuring its operations, focusing on a more efficient fleet, enhanced holiday package economics, and rigorous cost management. The board is confident that the company is nearing the realization of these efforts, suggesting that Castlelake's bid is opportunistic, seeking to benefit from the impending rebound.
A significant component of easyJet's strategy is its fleet modernization plan. The airline is slated to receive 90 new Airbus neo-family aircraft by fiscal year 2028, while simultaneously phasing out 79 older A319 planes. These newer aircraft offer improved fuel efficiency, greater passenger capacity, and better overall economic performance per seat sold—critical factors for a low-cost airline's profitability. Furthermore, easyJet Holidays represents another promising asset. This division operates with minimal capital expenditure, is experiencing rapid growth, and aims to achieve an annual pre-tax profit of £450 million by 2030. In an industry known for its capital intensity and operational challenges, a high-margin holiday business provides a valuable diversification beyond traditional air travel.
This explains why the board considers the 625 pence offer inadequate. easyJet is targeting over £1 billion in medium-term pre-tax profit, and analysts have frequently highlighted the substantial value of its aircraft and airport slots, particularly those at capacity-constrained airports, which are often compared to prime real estate. The airline's balance sheet strength is also a key consideration. easyJet has diligently worked to maintain financial flexibility, a vital buffer against the inherent uncertainties of the aviation industry, such as fuel price volatility, adverse weather, air traffic control issues, and shifts in consumer confidence. A debt-laden buyout, the board fears, could severely compromise this hard-won flexibility. Ultimately, the dispute centers on timing: Castlelake perceives an undervalued public company, while easyJet sees an attempt to acquire it just as its strategic plan is poised to yield significant returns. Both perspectives may hold merit, but only one will ultimately prevail in securing control of the airline.
The next critical juncture for Castlelake is Friday at 5 p.m., the deadline under the UK Takeover Code either to present a firm offer or withdraw its interest. In the interim, easyJet's leadership is expected to engage with major institutional shareholders, advocating for the superior long-term potential of its standalone strategy compared to Castlelake's cash bid. The central question remains whether Castlelake will increase its offer, potentially triggering a significant shareholder confrontation, or if easyJet will need to demonstrate the wisdom of its refusal to the market.