Analyst Perspectives on Arlo Technologies (ARLO) Performance and Future Outlook
Money

Analyst Perspectives on Arlo Technologies (ARLO) Performance and Future Outlook

authorBy Dave Ramsey
DateJun 20, 2026
Read Time3 min
This article delves into the latest analyst evaluations of Arlo Technologies (ARLO), exploring their ratings, price targets, and the underlying reasons for their optimistic forecasts. It highlights Arlo's strategic pivot towards a service-based revenue model and its impressive financial performance, offering insights into its potential as an investment.

Arlo Technologies: A New Horizon in Smart Home Security Investment

Oppenheimer's Bullish Stance: A Deep Dive into Arlo's Potential

Arlo Technologies, Inc. (NYSE:ARLO) has captured significant attention from financial analysts, with Oppenheimer leading the charge by initiating coverage with an "Outperform" rating and an ambitious $20 price target. This positive assessment is rooted in Arlo's remarkable transformation from a conventional camera manufacturer to a sophisticated, service-oriented recurring revenue platform. The firm underscored the company's adept navigation of the consumer hardware market, highlighting its success in cultivating a premium brand image and expanding its network of strategic distribution allies.

The Strategic Evolution: From Hardware to High-Value Services

Oppenheimer's analysis points to Arlo's successful business model evolution as a key driver of its future growth. The company's strategic shift has enabled it to transition from offering low-cost hardware to providing high-value, recurring services. This pivot is supported by a growing ecosystem of smart home security solutions, including cloud-based platforms and advanced surveillance devices. The analyst's report emphasized the accelerating momentum of Arlo's subscription services and identified a significant undervaluation of the company's service-mix profile in the current market.

Impressive Financial Metrics: A Testament to Growth

The financial performance of Arlo Technologies further solidifies its promising outlook. The company's annual recurring revenue (ARR) surged by 28% in 2025, reaching a substantial $330 million. This impressive growth underscores the efficacy of Arlo's service-centric strategy and its ability to generate consistent revenue streams. The first quarter of 2026 continued this upward trajectory, with subscriptions and services revenue climbing 30.9% year-over-year to $90.1 million, and ARR hitting $356.9 million, marking a 29.2% increase. Adjusted EBITDA also saw an remarkable 85.3% rise to $30.4 million, with non-GAAP EPS reported at $0.28.

Expanding Horizons: Innovations in Smart Home Security and Beyond

Arlo's leadership is actively pursuing strategic initiatives to broaden its market reach and enhance its service offerings. CEO Matthew McRae highlighted the acquisition of Aloe Care Health as a pivotal step towards expanding the company's AI-powered aging-in-place services. This move positions Arlo to tap into the growing market for elder care technology, further diversifying its revenue streams and reinforcing its commitment to innovation in smart home security and beyond.

A Comprehensive Overview of Arlo Technologies' Core Business

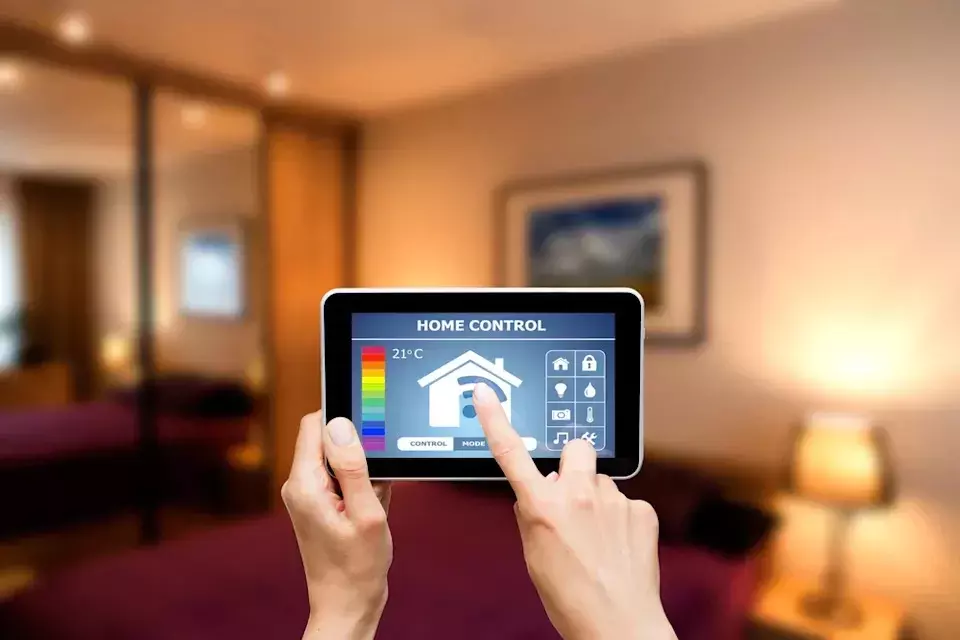
Arlo Technologies, Inc. stands as a leading innovator in the smart home security sector. The company specializes in developing and marketing a comprehensive suite of cloud-based platforms, wireless security cameras, video doorbells, floodlights, and alarm systems. These products and services cater to a diverse clientele, including both residential and commercial users, providing advanced solutions for safety and surveillance.
More Articles
Money
Cellebrite's Market Potential: Insights from DA Davidson's Bullish Outlook
DA Davidson initiates coverage on Cellebrite DI Ltd. (NASDAQ:CLBT) with a 'Buy' rating and a $20 price target, citing a large, growing, and potentially underestimated total addressable market. This positive assessment follows Cellebrite's strong Q1 2026 results, which saw significant revenue and Annual Recurring Revenue growth.
By Bola SokunbiJun 20, 2026
Money
Hyperliquid's Future: Navigating a Shifting Regulatory Landscape in Crypto Futures
Hyperliquid (HYPE) has seen a remarkable 194% surge, yet its future faces uncertainty with new competitors like Kalshi, Coinbase, and Robinhood entering the regulated U.S. perpetual futures market. Previously, U.S. customers lacked access to such platforms, but regulatory shifts are leveling the playing field. Hyperliquid's potential success depends on its ability to adapt to these changes and navigate the CFTC review process, making its continued high returns questionable.
By Dave RamseyJun 20, 2026
Money
Yum! Brands Divests Pizza Hut: Investor Concerns Arise
Yum! Brands recently announced the sale of Pizza Hut for $2.7 billion, a move that raises questions for investors despite its potential benefits. While the divestiture could allow management to concentrate on more successful brands like KFC and Taco Bell, it significantly reduces the company's brand diversification. With Pizza Hut's declining sales performance in recent years, the sale might appear strategic, yet it introduces new vulnerabilities for Yum! Brands as it becomes more reliant on its remaining core concepts. Investors should carefully evaluate the long-term implications of this reduced diversification in a consumer-driven market where brand popularity is cyclical.
By Ramit SethiJun 20, 2026
Money
ADMA Biologics Faces Federal Securities Lawsuit Amid Revenue Manipulation Claims
ADMA Biologics is currently embroiled in a federal securities lawsuit. The suit alleges the company inflated revenues for its primary product through "channel stuffing" and concealed a distribution partnership connected to an entity supposedly under the control of a senior executive. These accusations surfaced following a critical report by Culper Research, causing a significant drop in ADMA's stock value, despite some analysts' optimistic outlooks.
By Chika UwazieJun 20, 2026
Money
U.S. vs. Global Real Estate ETFs: A Comparative Analysis of XLRE and RWO
This article compares two prominent real estate exchange-traded funds (ETFs): State Street Real Estate Select Sector SPDR ETF (XLRE) and State Street SPDR Dow Jones Global Real Estate ETF (RWO). It delves into their cost structures, portfolio compositions, geographic focus, and overall investment strategies, offering insights for investors contemplating domestic versus international real estate exposure. The analysis highlights XLRE's U.S.-centric, lower-cost approach against RWO's global diversification with a higher expense ratio, emphasizing key considerations for long-term income seekers.
By Dave RamseyJun 20, 2026